Introduction
The 2026 Canadian proxy season was marked by continued investor support for directors and executive compensation, alongside evidence of sustained engagement on a range of governance and strategic issues. Directors and executive compensation proposals continued to receive strong investor backing, with support levels remaining broadly consistent with recent years and few instances of significant shareholder opposition. At the same time, shareholder engagement remained active, as reflected in record proposal volumes and continued scrutiny of corporate governance practices, meeting formats, and strategic transactions.
While support for management-sponsored resolutions remained high, several developments suggest investors are continuing to use available governance mechanisms to express preferences and shape corporate practices. Rising volumes of board- and compensation-related shareholder proposals, the sustained preference for in-person and hybrid annual meetings, and ongoing interest in significant merger and acquisition activity all point to a governance landscape that continues to evolve even amid broadly stable voting outcomes.
Director Elections
Directors continue to receive strong shareholder support. To date in 2026, only two nominees failed to secure majority support, while an additional 11 received less than 60 percent. Average support stood at 96.7 percent. By comparison, 18 nominees failed to receive majority support in 2025, with a further nine falling below 60 percent and average support at 96.4 percent.
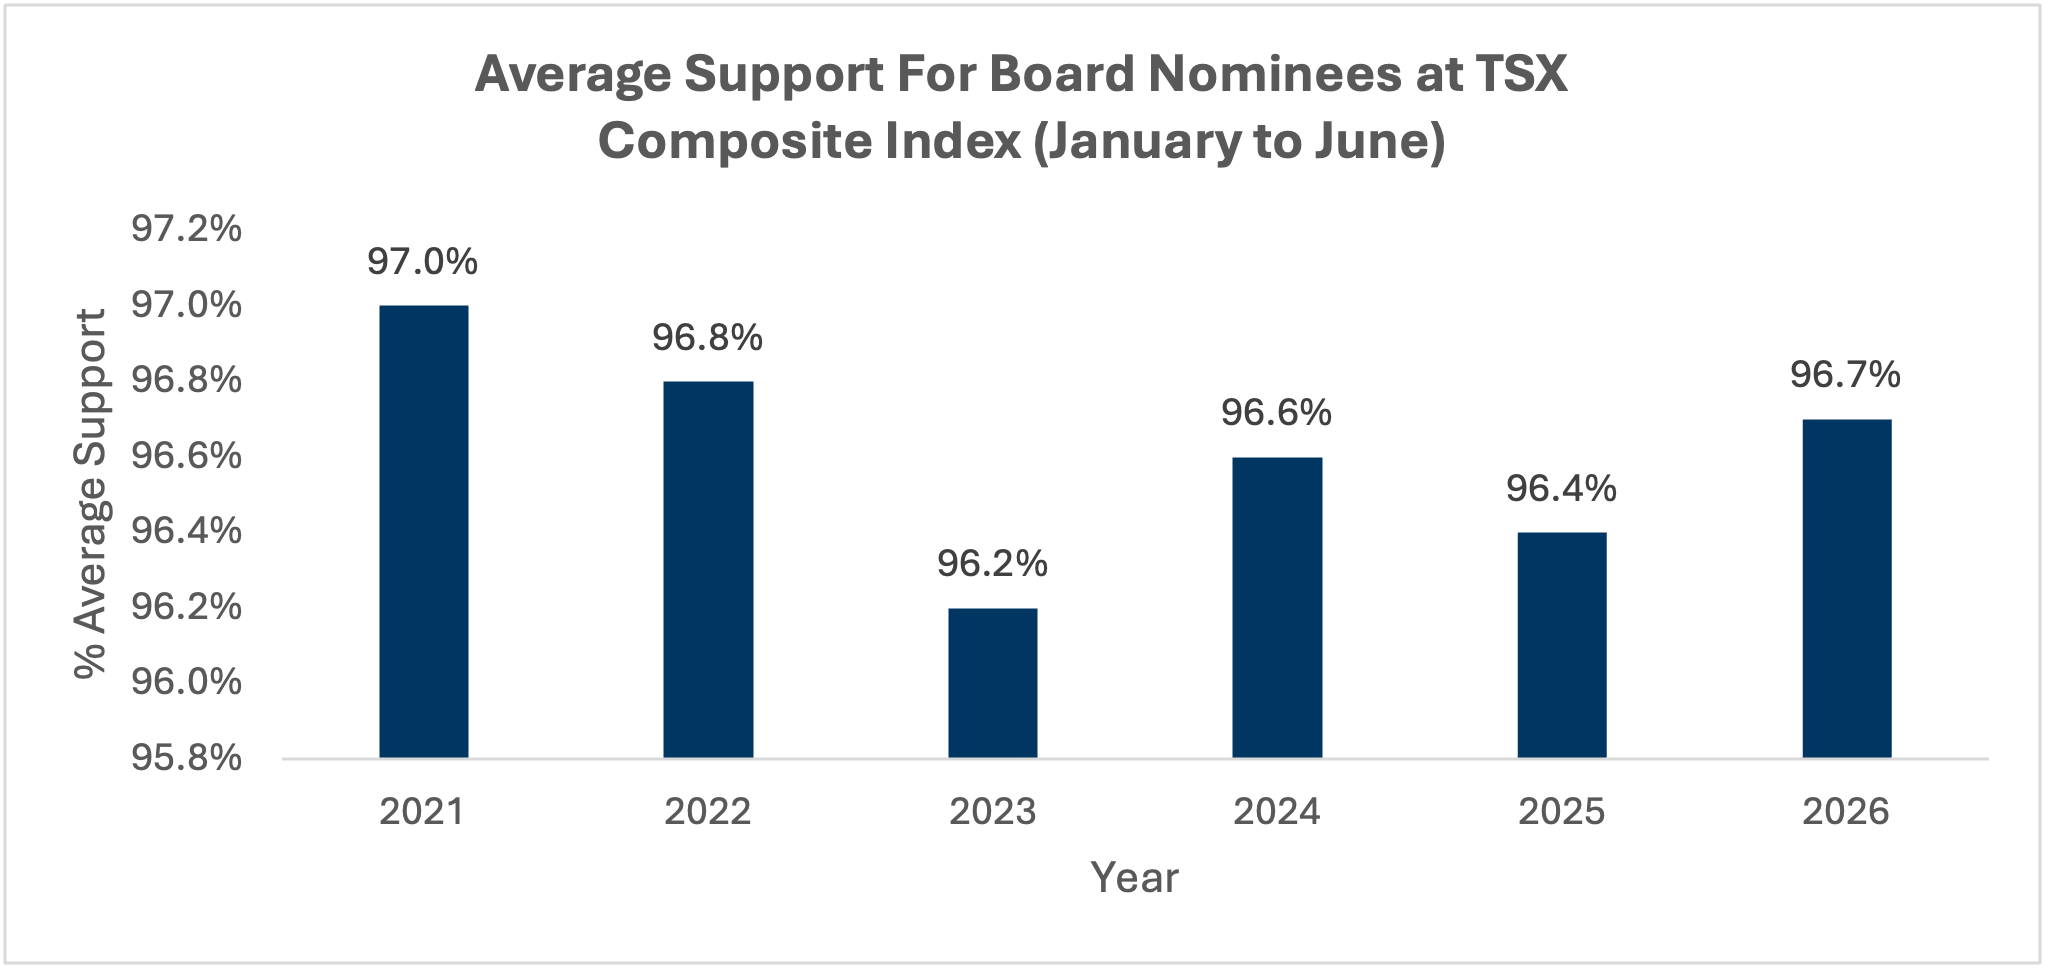
None of the directors at S&P/TSX Composite Index companies received less than majority support at uncontested elections in 2024.
Executive Compensation
Shareholder support for compensation practices remains high in Canada. To date in 2026, only one company has failed to receive majority support for its say-on-pay resolution, compared with three companies in all of 2025. Thirteen companies have received less than 80 percent support so far this year, versus 15 for the full year of 2025. Average support stood at 93.5 percent in 2026 and 92.8 percent in 2025.
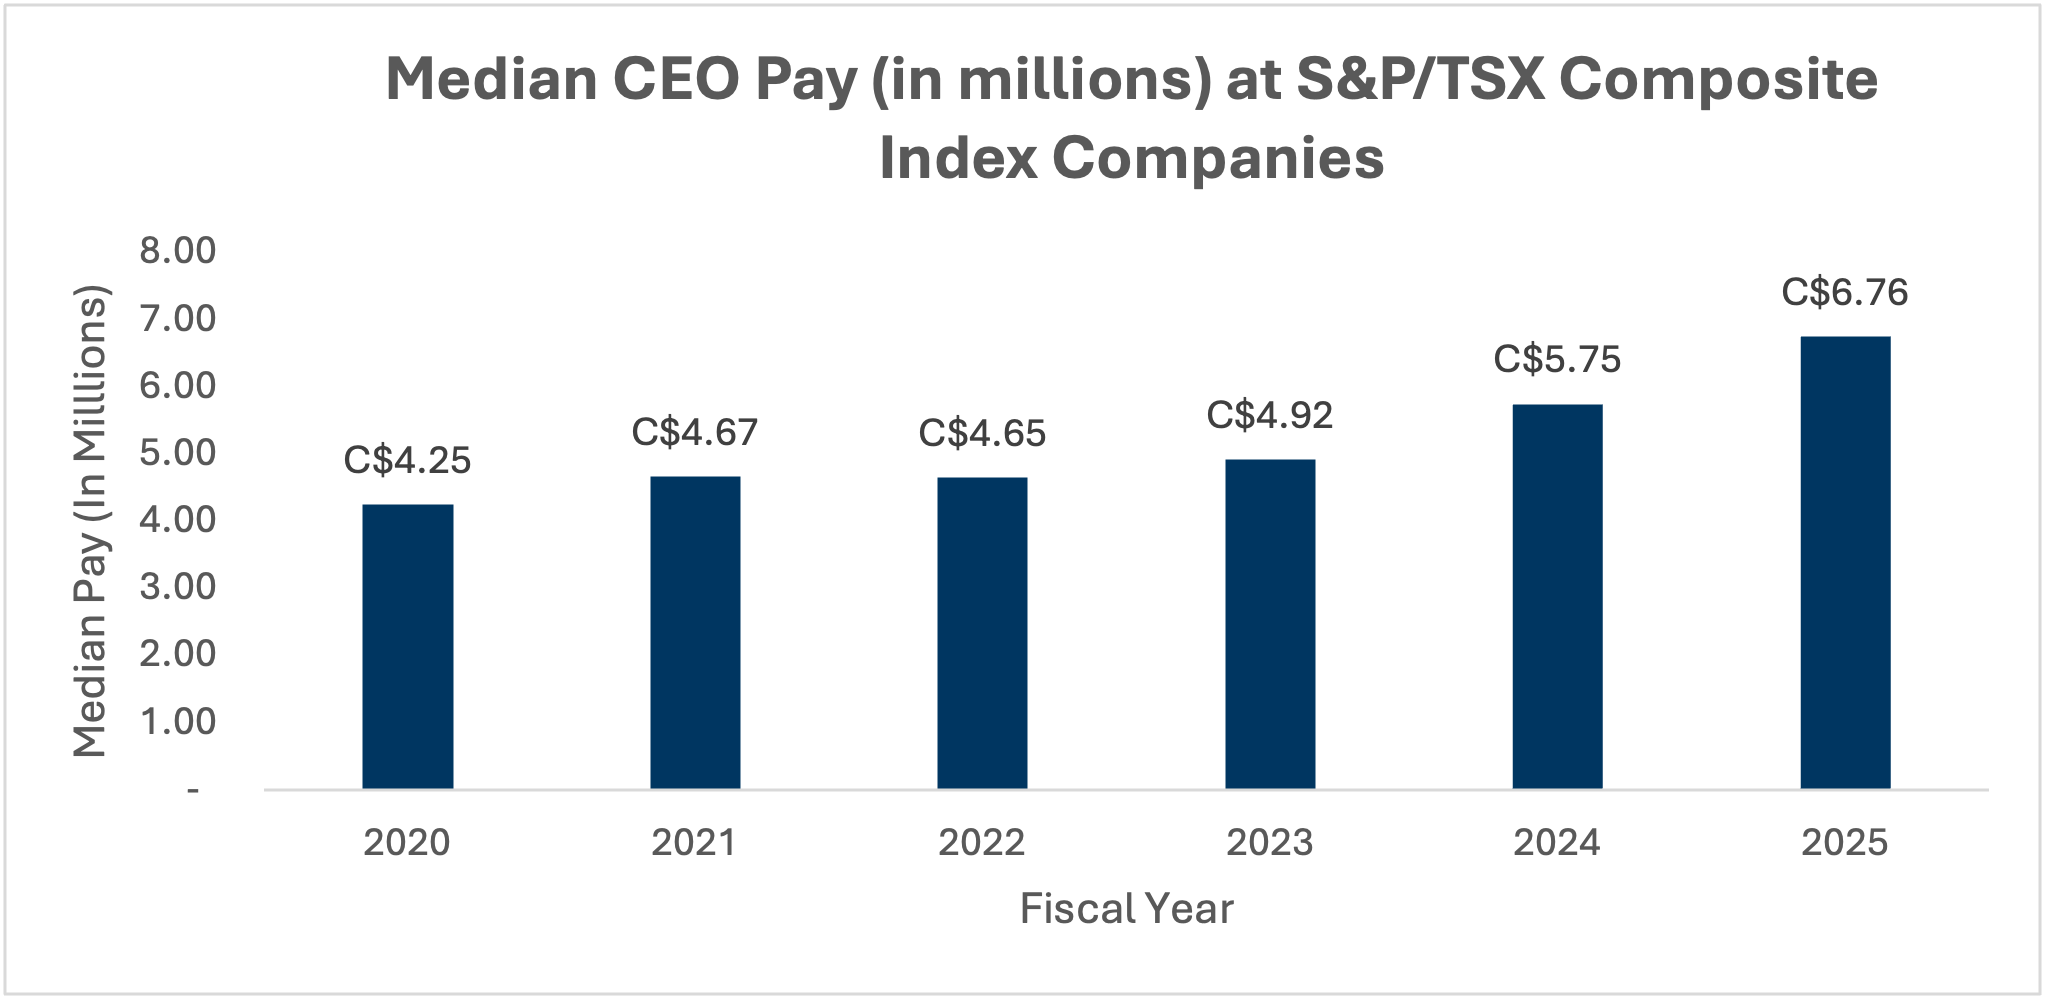
Meanwhile, median CEO compensation during fiscal year 2025 at S&P/TSX Composite Index companies increased relative to fiscal 2024 and notably reached the highest levels in the last six years after a slight decrease in fiscal 2022.
Shareholder Proposals
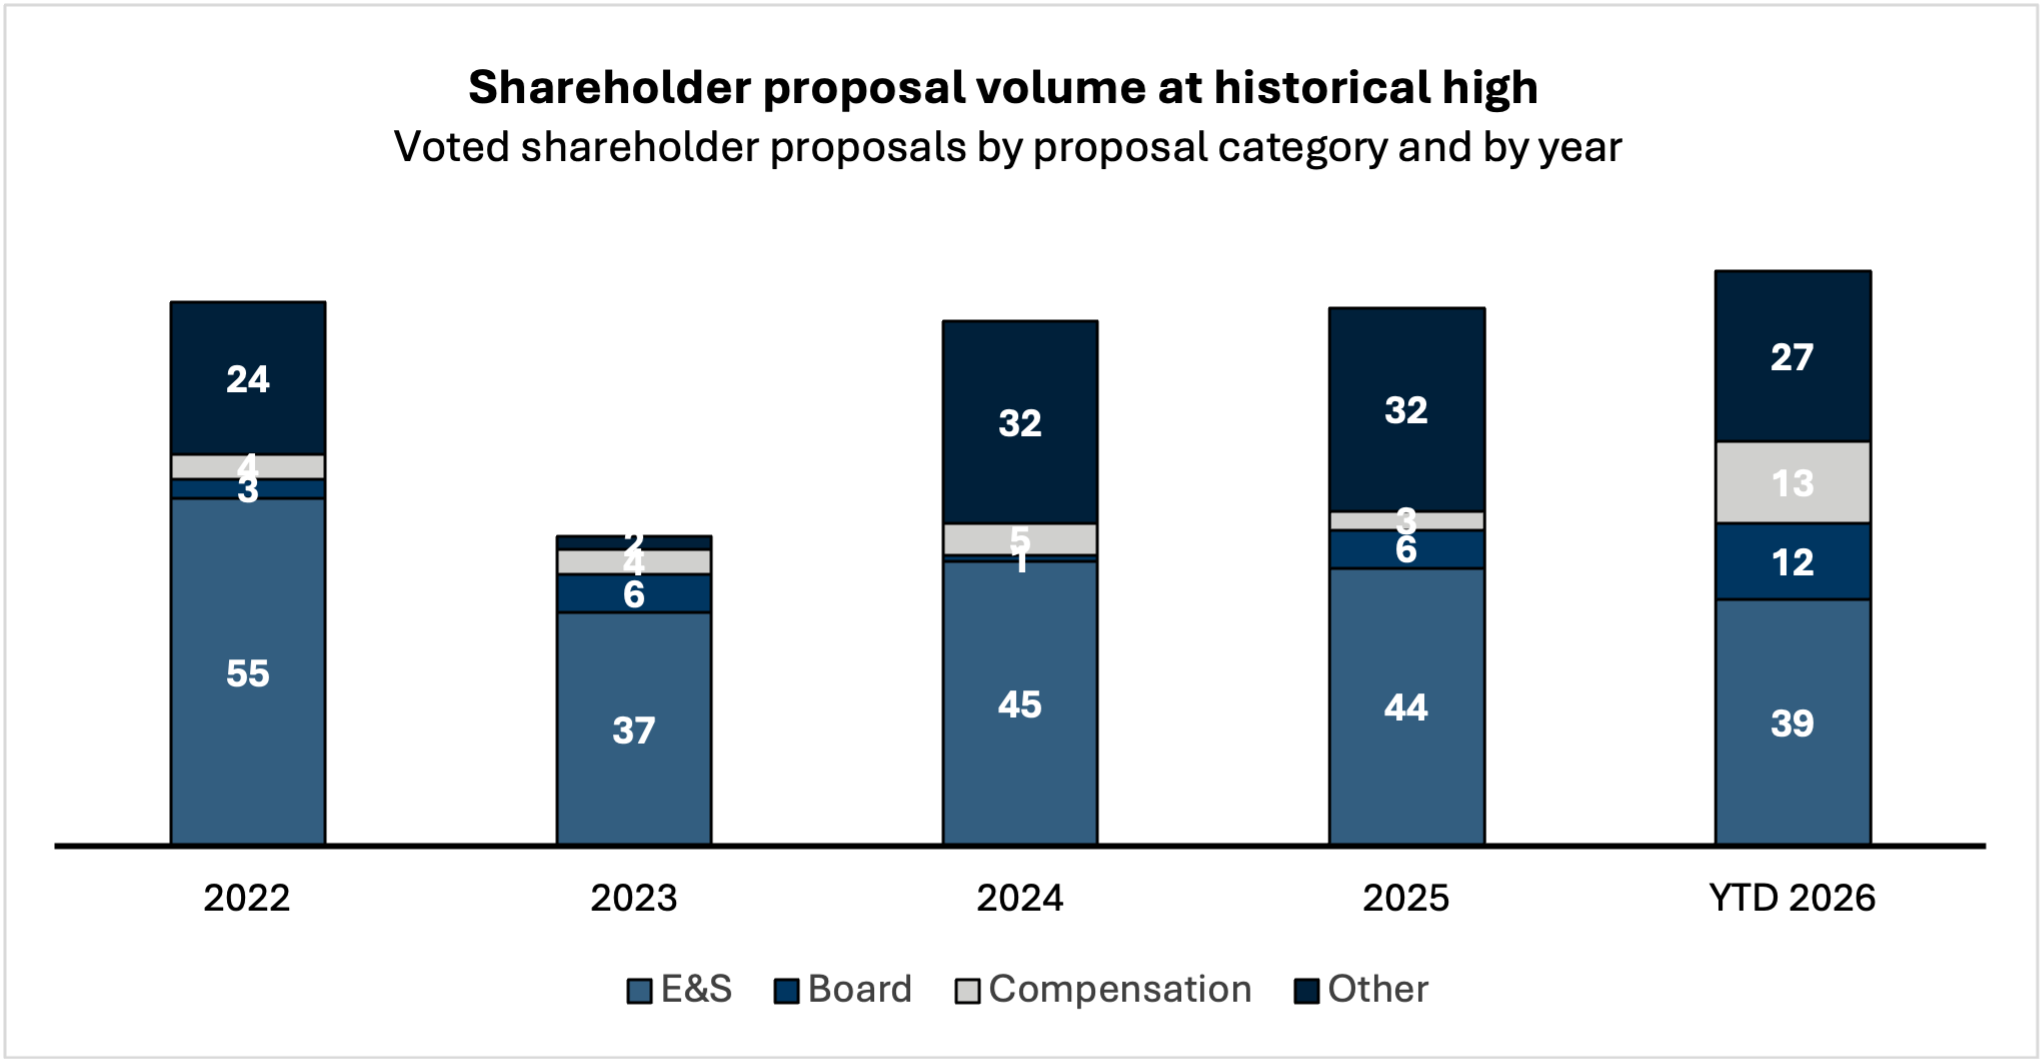
Shareholder proposal volumes reached an all-time high in 2026. To date, 91 proposals have appeared on ballots. While the number of E&S proposals declined, board- and compensation-related proposals rose sharply, from nine in 2025 to 25 in 2026.
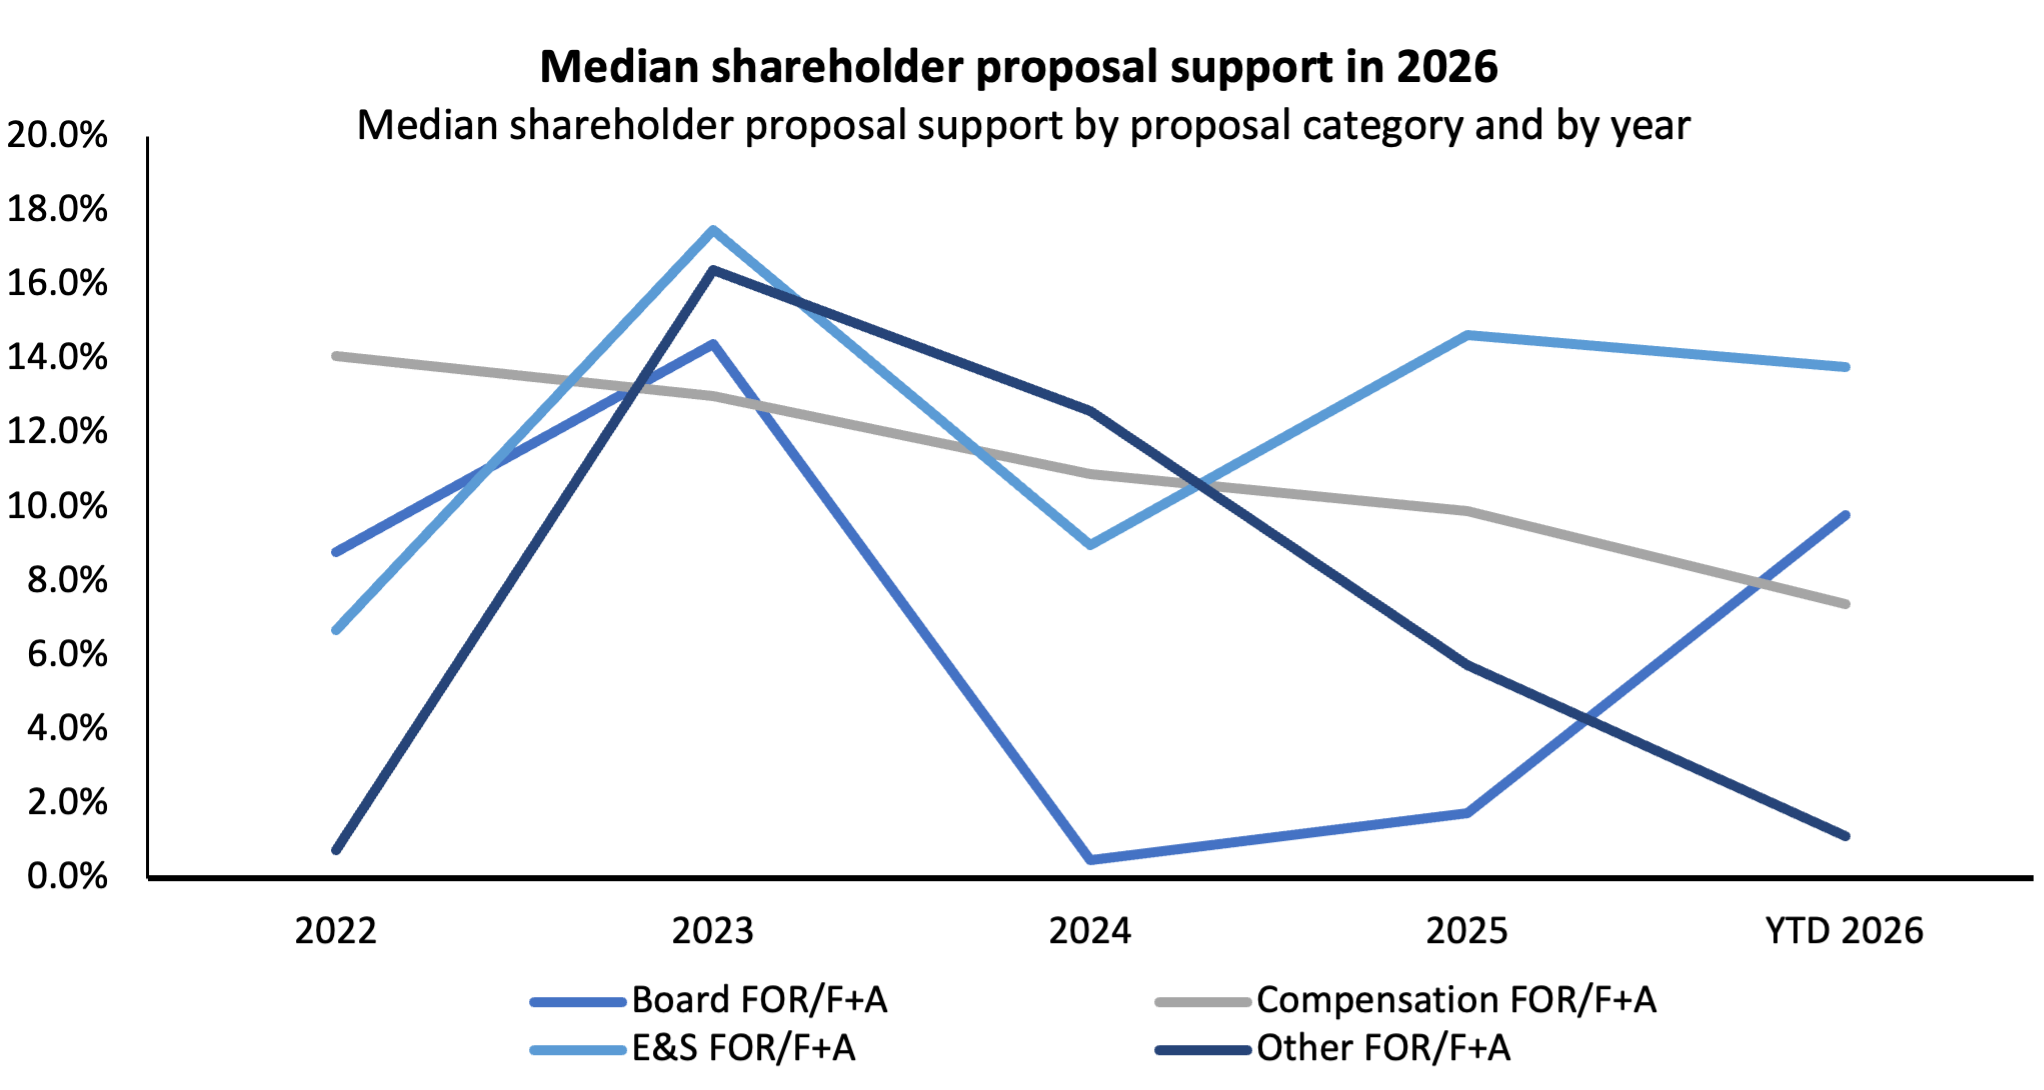
Overall vote support for shareholder proposals remains muted. E&S proposals continue to attract the highest support, with a median of around 14 percent. Board-related proposals recorded the largest increase, rising to a median of approximately 10 percent from just 2 percent in 2025.
Virtual Meetings
Shareholder pressure to move away from the virtual-only format continues to influence corporate practice. The percentage of S&P/TSX Composite Index companies holding virtual-only meetings remained steady in 2026 at 42 percent, meaning 58 percent of Index companies held in-person or hybrid meetings. This marks the second consecutive year in which in-person and hybrid meetings have outnumbered virtual-only meetings. Prior to this shift, and since the widespread adoption of the virtual-only format in Canada in 2020, the majority of Index company meetings had been conducted virtually.
High Profile Meetings and M&A Activity
GFL Environmental’s approximately $6.4 billion acquisition of SECURE Waste Infrastructure Corp. encountered opposition from Abrams Capital, which held roughly 10 percent of SECURE’s shares at the time. Despite this resistance, the transaction secured strong backing from the broader shareholder base. At the special meeting held on May 27, 2026, approximately 79 percent of votes cast were in favor of the deal.
Separately, Thoma Bravo is acquiring kneat.com, inc. in an all-cash take-private transaction valued at approximately $650 million. Shareholders will vote on this transaction on July 30, 2026. While more modest in scale, the deal is the latest example of a TSX-listed technology company, particularly in the software sector, exiting the public markets. A significant share of the Canadian tech firms that went public on the TSX during the 2020–2021 boom have since been taken private. Thoma Bravo has been notably active in this space, having previously acquired Magnet Forensics for $1.8 billion in 2023, less than two years after that company’s IPO.
Conclusion
The 2026 Canadian proxy season highlighted a market characterized by strong investor support for boards and executive compensation practices, alongside sustained shareholder engagement on governance matters. Director election and say-on-pay results remained robust, with few instances of material opposition, reflecting voting outcomes that were broadly consistent with recent years.
At the same time, record shareholder proposal volumes, shifts in proposal topics, and the continued prevalence of in-person and hybrid meetings demonstrate that investors remain focused on influencing governance practices through a range of channels. Meanwhile, notable transaction activity underscored the importance of shareholder oversight in evaluating significant corporate events and strategic changes.
Authored By
ISS STOXX Governance
See More